IMARC Group has recently released a new research study titled "U.S. Edge Computing Market Size, Share, Trends and Forecast by Component, Organization Size, Vertical, and Region, 2026-2034", offering a detailed analysis of the market drivers, segmentation, growth opportunities, trends, and competitive landscape to understand the current and future market scenarios.
U.S. Edge Computing Market Size & Share 2026-2034
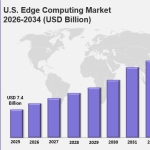
The U.S. edge computing market size reached USD 7.4 Billion in 2025. Looking forward, IMARC Group estimates the market to reach USD 49.6 Billion by 2034, exhibiting a CAGR of 22.76% from 2026-2034. The market is witnessing notable expansion, influenced by elevating need for real-time data processing, low-latency solutions, and IoT expansion.
Crucial segments like retail, healthcare, and manufacturing are leveraging edge technologies to improve operational efficacy, data safety, and adherence with transforming privacy policies, further shaping the U.S. edge computing market share.
Key Market Statistics at a Glance
- Base Year: 2025
- Historical Years: 2020-2025
- Forecast Period: 2026-2034
- Market Size (2025): USD 7.4 Billion
- Projected Market Size (2034): USD 49.6 Billion
- Growth Rate: CAGR of 22.76% (2026-2034)
Explore Opportunities in the U.S. Edge Computing Market: Download the IMARC Sample Report: https://www.imarcgroup.com/united-states-edge-computing-market/requestsample
Key Growth Drivers and Trends in the U.S. Edge Computing Market
Growth in the U.S. edge computing market is being driven by magnifying dependence on real-time applications across manufacturing, healthcare, and finance, addressing minimal latency requirements. Edge computing mitigates delays by facilitating local data processing, requisite for crucial applications including predictive maintenance, telemedicine, and financial transactions. In October 2024, IBM launched Granite 3.0, featuring high-performing AI models designed for business, with Granite Guardian 3.0 elevating AI safety and new Mixture-of-Experts models facilitating effective inference with low latency, ideal for CPU-based implementations and edge computing applications.
One of the leading U.S. edge computing market trends is amplifying adoption of IoT devices, as businesses actively opt for edge computing to process data closer to IoT endpoints, improving real-time decision-making abilities and minimizing latency. In July 2024, VIA Technologies joined forces with Rutronik to expand access to computer vision, edge AI, and cutting-edge IoT solutions across commerce, industrial, and retail segments, with VIA's MediaTek Genio-powered platforms addressing diverse edge computing needs with reduced latency.
Another key factor supporting U.S. edge computing market growth is rapid proliferation of 5G networks, as per industry reports, 5G accounted for 37% of all wireless connections in North America in 2024. 5G facilitates minimized latency and swift data transfer speeds, establishing edge computing solutions as more effective for critical applications such as autonomous vehicles, augmented reality (AR), and virtual reality (VR), with telecom operators increasingly collaborating with edge solution firms to improve network abilities.
Speak to an Analyst: https://www.imarcgroup.com/request?type=report&id=11072&flag=C
U.S. Edge Computing Industry Segmentation Insights
Breakup by Component:
- Hardware: Dominates the market, encompassing edge servers, gateways, and sensors that play a crucial role in processing and storing data locally, minimizing latency and reducing dependency on centralized data centers.
- Software: Holds a significant share, driven by the need for platforms enabling efficient data management, analytics, and application deployment at the edge, including edge orchestration, virtualization, and AI-driven software.
- Services: Covers consulting, deployment, and managed services supporting enterprises in designing and implementing edge infrastructure tailored to their specific needs.
Breakup by Organization Size:
- Large Enterprises: Dominates the market due to significant investments in advanced technologies and infrastructure supporting complex applications such as AI-driven analytics, autonomous systems, and industrial IoT.
- Small and Medium-sized Enterprises (SMEs): Represents a growing segment driven by the need for cost-effective, scalable solutions to enhance operational efficiency and support IoT and AI-based applications within budget constraints.
Breakup by Vertical:
- Manufacturing: Holds a substantial share, driven by increasing adoption of smart factories and Industry 4.0 technologies spurring demand for real-time data processing and predictive maintenance.
- Energy and Utilities: Utilizes edge solutions for smart grids, renewable energy integration, and predictive maintenance of infrastructure.
- Government and Defense: Leverages edge computing for national security, disaster response, surveillance, and mission-critical operations.
- BFSI: Uses edge computing to enhance customer experience, fraud detection, and risk management through real-time financial data processing.
- Telecommunications: A major adopter driven by 5G network rollout and demand for ultra-low latency applications.
- Media and Entertainment: Leverages edge computing to enhance content delivery, live streaming, and gaming experiences.
- Retail and Consumer Goods: Adopts edge computing to enhance customer engagement, inventory management, and supply chain efficiency.
- Transportation and Logistics: Reshaped by edge computing through route optimization, real-time tracking, and predictive maintenance of fleets.
- Healthcare and Life Sciences: A key adopter utilizing edge computing for telemedicine, remote monitoring, and real-time diagnostic applications.
- Others: Includes additional verticals adopting edge computing solutions across the economy.
Breakup by Region:
- Northeast: Holds a notable share, driven by dense population centers and thriving industries like finance, healthcare, and education, with major metropolitan areas like New York and Boston serving as technology deployment hubs.
- Midwest: Bolstered by expanding manufacturing and logistics industries, with states like Illinois and Michigan leading in edge adoption for predictive maintenance and supply chain optimization.
- South: Commands a significant share, driven by rapid advancements in energy, healthcare, and retail sectors, with Texas and Florida as key contributors.
- West: Plays a significant role due to its prominence in technology and innovation, home to Silicon Valley and key technology firms in California and Washington.
Key Challenges and Growth Opportunities in the U.S. Edge Computing Market
The U.S. edge computing market faces challenges including implementation complexity and high initial infrastructure costs, along with ensuring data security and compliance across distributed edge networks requiring sophisticated management tools and expertise, creating barriers particularly for small and medium enterprises.
Despite these challenges, the market offers considerable growth opportunities driven by the rapid proliferation of 5G networks enabling ultra-low latency applications including autonomous vehicles, AR/VR, and IoT implementations. Increasing emphasis on data privacy compliance driving demand for localized processing solutions is expected to create substantial opportunities across healthcare, finance, and government sectors for long-term growth in the U.S. edge computing market.
Competitive Landscape
The U.S. edge computing market is represented by intensified competition among major industry players, encompassing innovative startups, technology leaders, and cloud service firms, with acquisitions and collaborations extremely prevalent tactics to proliferate market foothold and improve abilities. In October 2024, Duos Edge AI formed a tactical partnership with Accu-Tech to bolster the implementation of edge computing ecosystem across the U.S., expected to facilitate increased proliferation of edge computing abilities catering to amplifying need for enhanced connectivity and low-latency data processing in untapped markets.
Recent Developments in the U.S. Edge Computing Market
- September 2025: ADLINK Technology launched a new portfolio of industrial computing platforms powered by Intel Core 200S series processors, covering Mini-ITX, ATX, PICMG 1.3, COM-HPC, and edge AI systems, optimized for industrial automation, robotics, transportation, gaming, and medical imaging applications.
- September 2025: Premio launched the JCO-1000-ORN, a rugged, fanless edge AI computer powered by NVIDIA Jetson Orin NX and Nano modules, designed for harsh industrial environments, supporting real-time AI inferencing with up to 157 TOPS performance.
- October 2024: ZEDEDA and OnLogic partnered to introduce OnLogic Powered by ZEDEDA, integrating OnLogic's durable industrial hardware with ZEDEDA's cloud-native edge orchestration software, delivering a robust platform enabling enterprises to scale, maintain, and deploy edge computing workloads securely.
- February 2024: Casey's General Stores Inc. collaborated with Acumera Reliant Platform to aid its edge computing and digital transformation ventures, facilitating expandable technology across 2,600 or more U.S. locations.
Author IMARC Group
IMARC Group is a leading global market research company providing data-driven insights and expert consulting services to businesses seeking to achieve their strategic objectives. With a multidisciplinary team of industry experts, IMARC delivers reliable market intelligence across sectors including Chemicals and Materials, Healthcare, Technology, Agriculture, and Retail.
Contact Us:
IMARC Group
Email: sales@imarcgroup.com
United States: +1-201-971-6302